Payslips don't tell the whole story when you run your own business. We know how to present your income so lenders actually understand it.
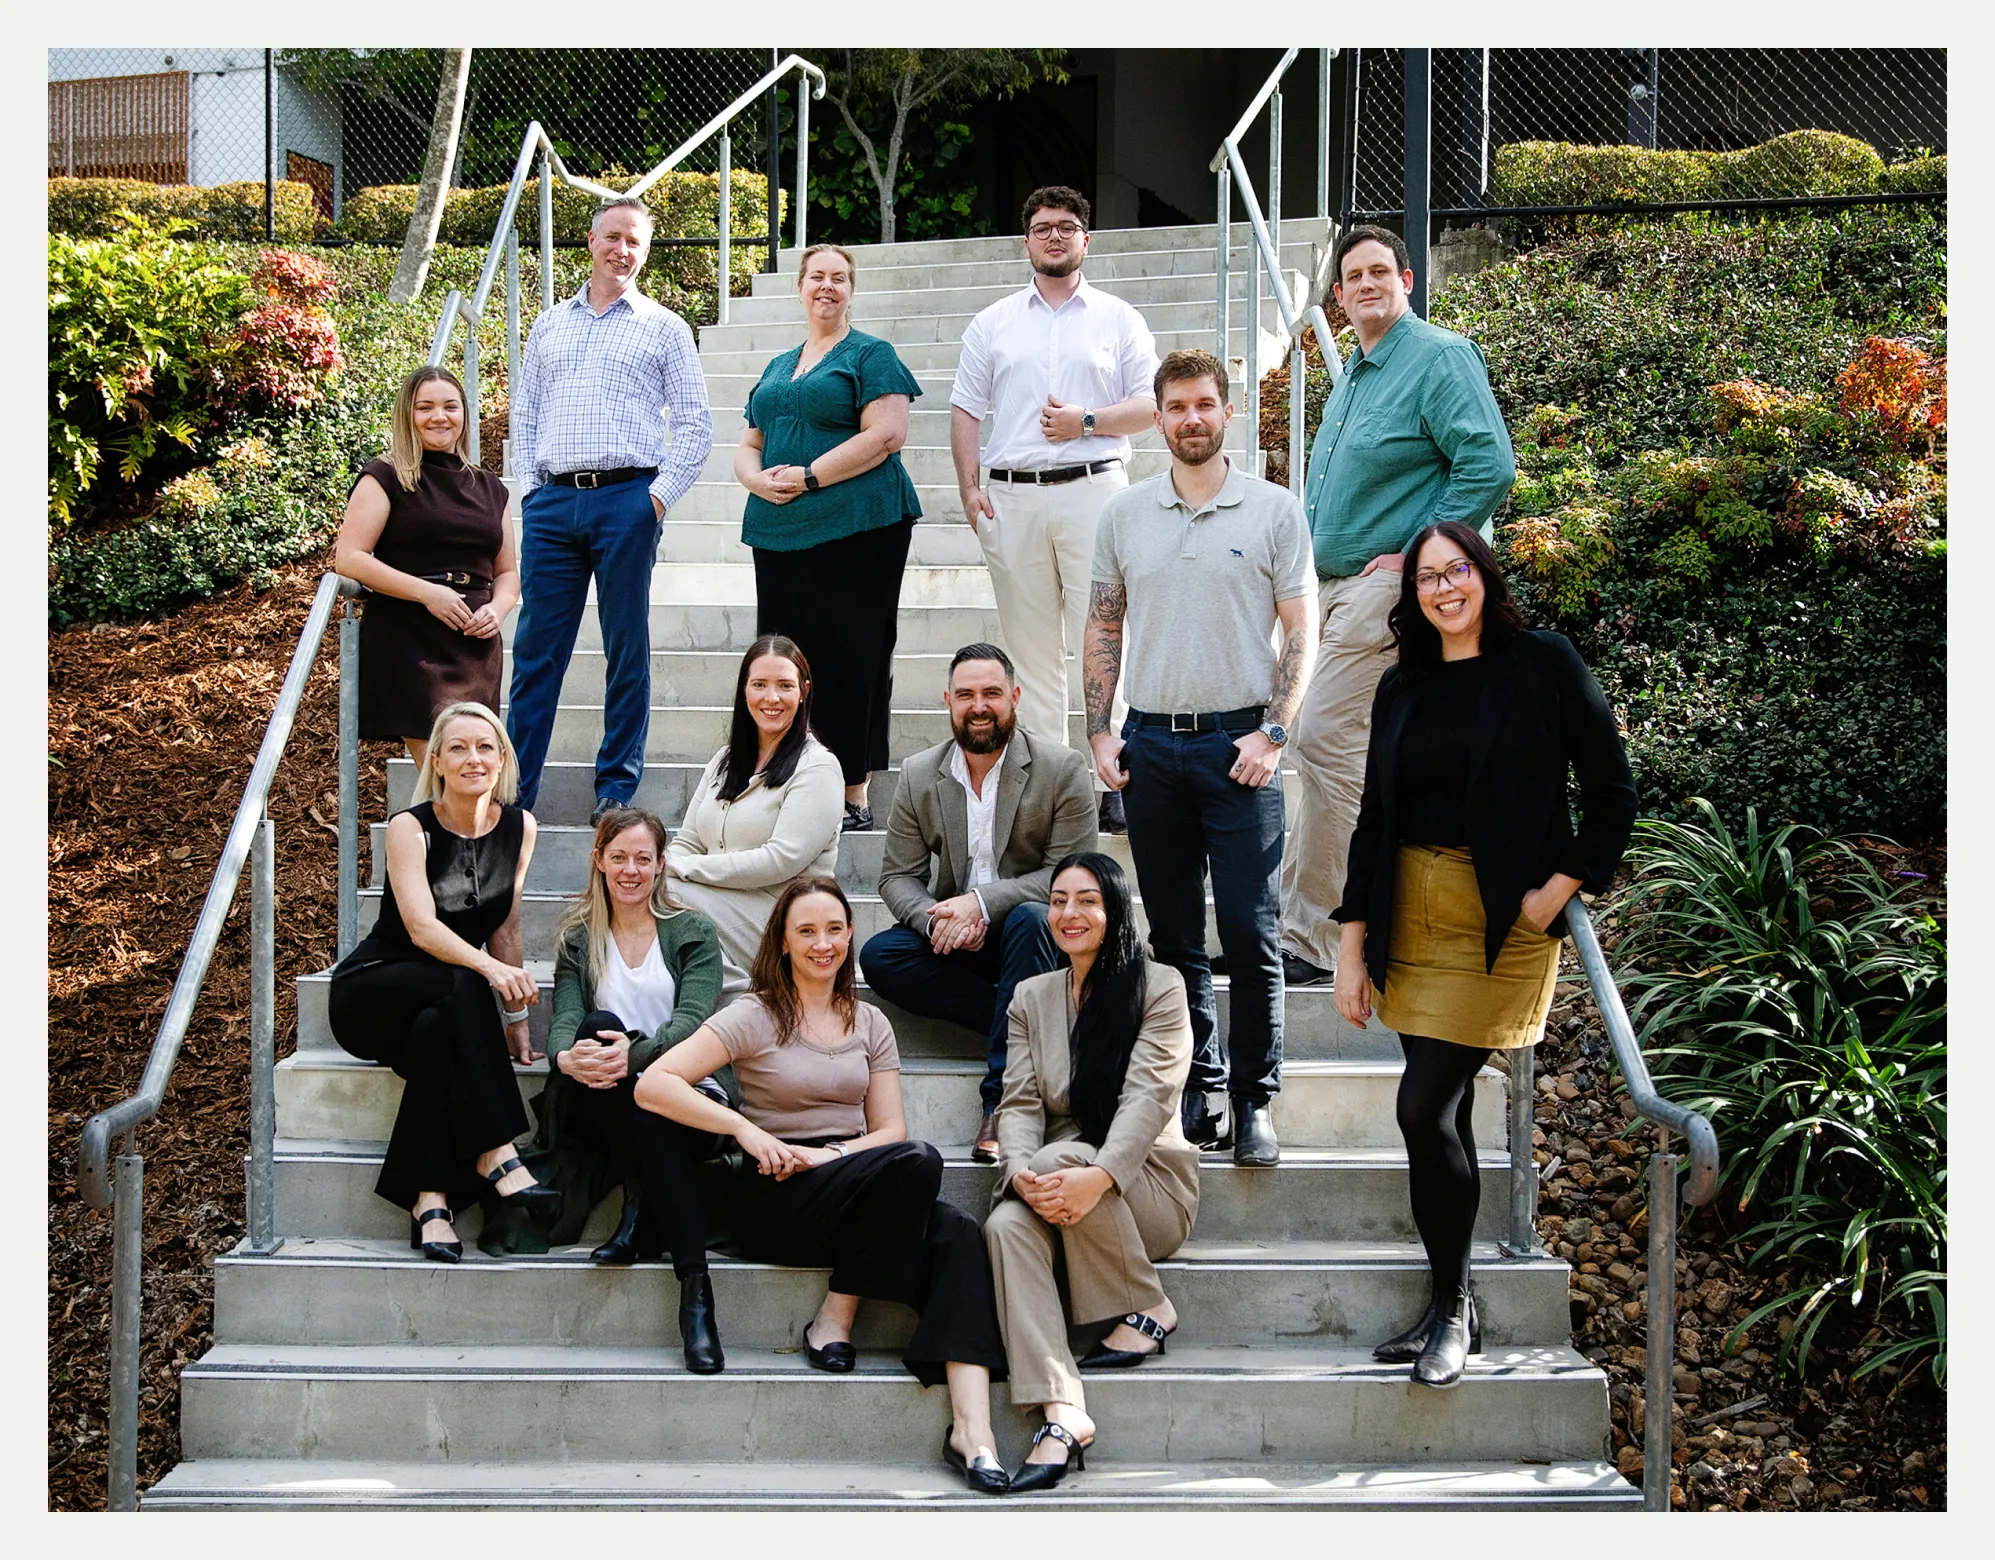
Meet Mel and the Zest team, who've helped hundreds of self-employed clients get their finance approved.
When you work for yourself, a payslip does not tell the whole story, so lenders turn to your tax returns and business financials instead. Some will work from one year of tax returns while others want two, and add-backs are treated differently from lender to lender. The same set of numbers can produce a very different borrowing capacity depending on who assesses it.
We take the time to understand how your business earns its income and present it so lenders can follow it. Then we compare 60+ lenders to find one that reads your numbers the way you do. We are based in Springfield and help self-employed clients across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe being self-employed shouldn't make getting a home loan any harder. Here are a few recent Zest Google reviews we think you'll love!

Start with a free chat with Mel & the team. We'll walk through your BAS, tax returns and business financials to figure out exactly what a lender will need to see.

Different lenders assess self-employed income differently, some use one year of tax returns, others want two, and add-backs are treated all sorts of ways. We compare across 60+ lenders to find one that reads your numbers the way you do.

Once we've found the right lender, we handle the application from start to finish, including liaising with your accountant for any extra paperwork along the way.


Our self-employed home loans suit sole traders, contractors, freelancers and anyone whose income doesn't come from a regular payslip. If you run a company or trust, see our business owner home loan page as well.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
Many Springfield and Ipswich locals are tradies, contractors and small business owners. We see how lenders treat self-employed income every week and know which ones are more flexible.
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
Many lenders want two years, but some accept one year of tax returns, depending on your history.
A low doc loan lets self-employed borrowers verify income using alternatives such as BAS, bank statements or an accountant's declaration instead of full tax returns. These loans often have higher rates.
It's harder, but some lenders offer alternatives. Getting your returns lodged first usually gives you more options.
Yes. Adding back items like depreciation can increase the income a lender uses, which can increase how much you can borrow.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


