Whether the kids have moved out or you're just ready for less maintenance, we'll help you work out what equity you can free up and what loan makes sense for your next chapter.
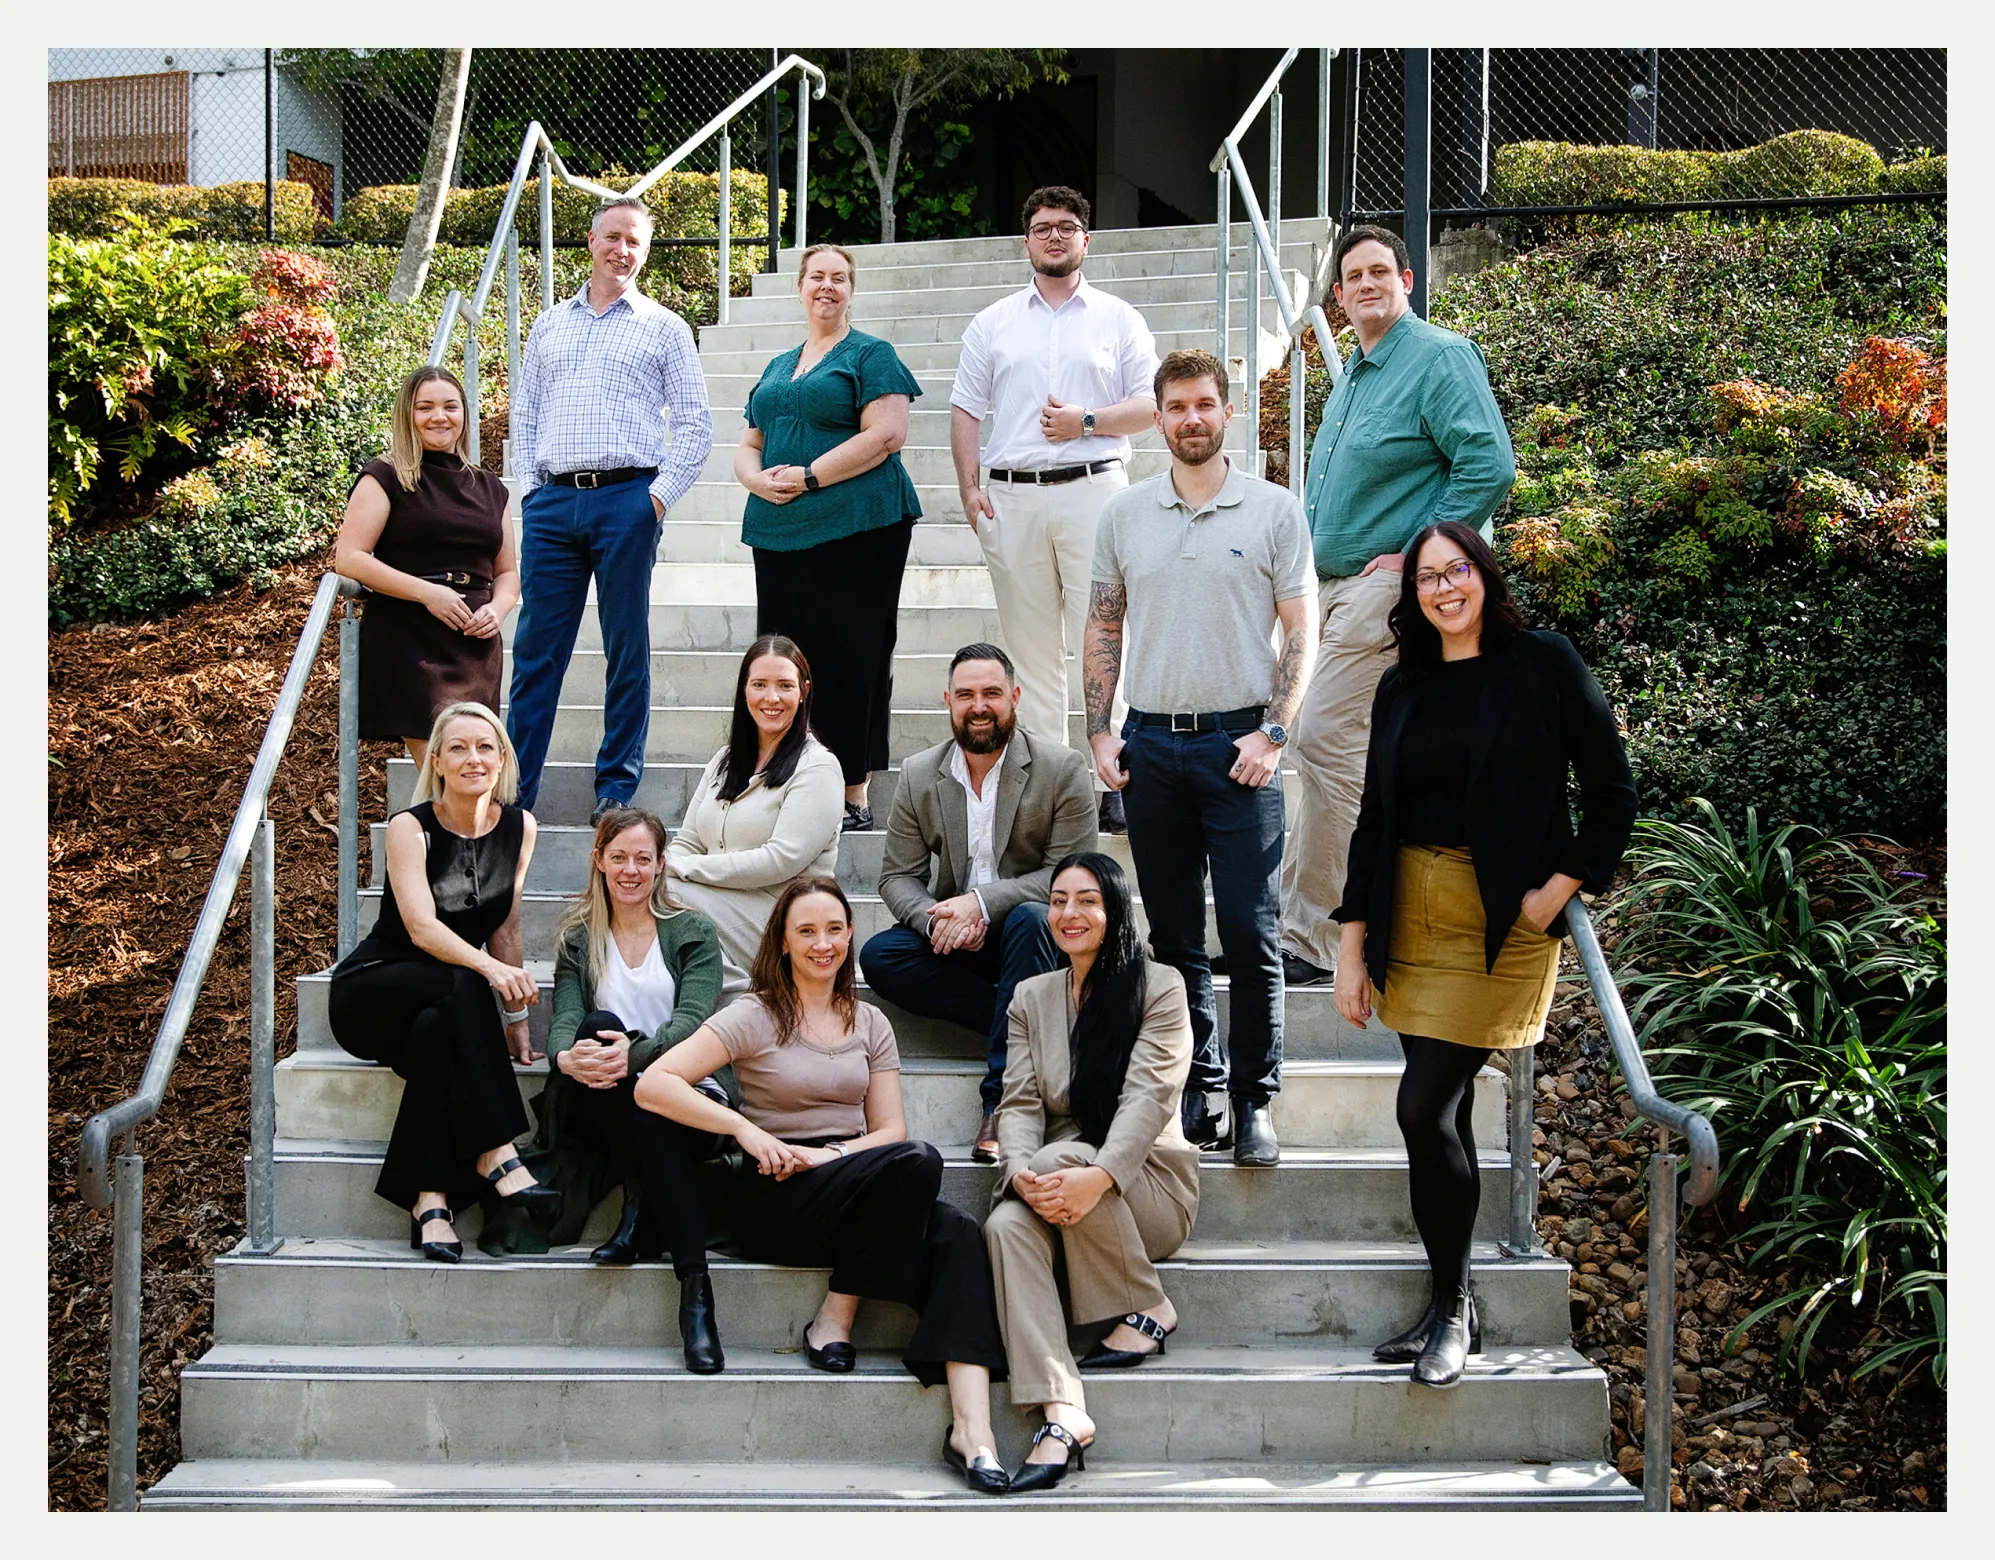
Meet Mel and the Zest team, who've helped hundreds of clients downsize into a home that suits their next chapter.
Downsizing can be more complex than it sounds. You may still have a mortgage to pay out, need finance in place before your current home sells, or want to work out how much equity you can free up. The order you buy and sell in matters, and the right structure, including bridging options, can take the pressure off.
We compare 60+ lenders to find a structure that suits your timing and your plans for what comes next. You deal directly with Mel and the team, who are based in Springfield and help downsizers across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe downsizing should be just as simple as finding the right next home. Here are a few recent Zest Google reviews we think you'll love!

A quick chat with Mel & the team is the best place to start. We'll look at your current equity, what you're hoping to achieve, and whether it makes more sense to sell first or buy first. No cost, no obligation.

Downsizing can be more complex than it sounds, especially if you're also paying off an existing mortgage or need finance in place before your current home sells. We compare across 60+ lenders to find a structure, including bridging options, that takes the pressure off.

Once we've sorted the finance side, we handle the application and paperwork so you can focus on the move itself. We'll also help you think through timing if you're coordinating a sale and purchase together.


A downsizing loan suits people moving to a smaller or lower-maintenance home, often once children have left or retirement is approaching. Some downsizers need a small loan to bridge the timing, while others want to keep some borrowing flexibility. If you want to buy before you sell, see bridging loans.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
Downsizers in the Springfield and Ipswich area often look for homes closer to shops, transport and health services, such as around Springfield Central or the Ipswich CBD. We help make sure your finance suits this next stage, not just the purchase.
Many downsizers expect to buy their next home outright, then find the timing does not line up. The home you want may come up before yours sells, or you may want a small loan to keep some savings in reserve. We look at whether you need finance at all, how much, and for how long, before you sign anything.
If you are borrowing later in life, lenders will ask how the loan will be repaid, especially if the term runs past your planned retirement. This is called an exit strategy, and it might be the sale of your current home, super, or other savings. Lenders also look closely at pension and super income. Having this explained clearly in your application makes a real difference, and we help you put it together.
We also talk through the order you buy and sell in, and whether a bridging loan makes sense. For questions about super contributions from the sale or the Age Pension, we suggest speaking with your financial adviser or accountant, as we only arrange the lending.
Downsizers we help often want to stay close to family, their GP and the shops they know. Some move to a lower-maintenance home in Brookwater or Springfield Lakes, or closer to the Ipswich CBD. Our guides to the best suburbs for downsizers and home loans for retirees cover the details, and you can meet Mel and the team at our Springfield office in Brookwater or our Ipswich office on East Street.
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
Yes, many lenders will lend to older borrowers, but they'll want to see how the loan will be repaid, such as through super or the sale of an asset.
Not always. If the sale of your home covers the new purchase, you may not need one, but short-term finance can help with timing.
Eligible Australians may be able to make a downsizer contribution to super. Speak with your financial adviser about whether it applies to you.
Allow for stamp duty, legal fees, agent fees, moving costs and any updates to your new home.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


