A bridging loan lets you secure your next property while your current one is still on the market, without needing everything to line up perfectly.
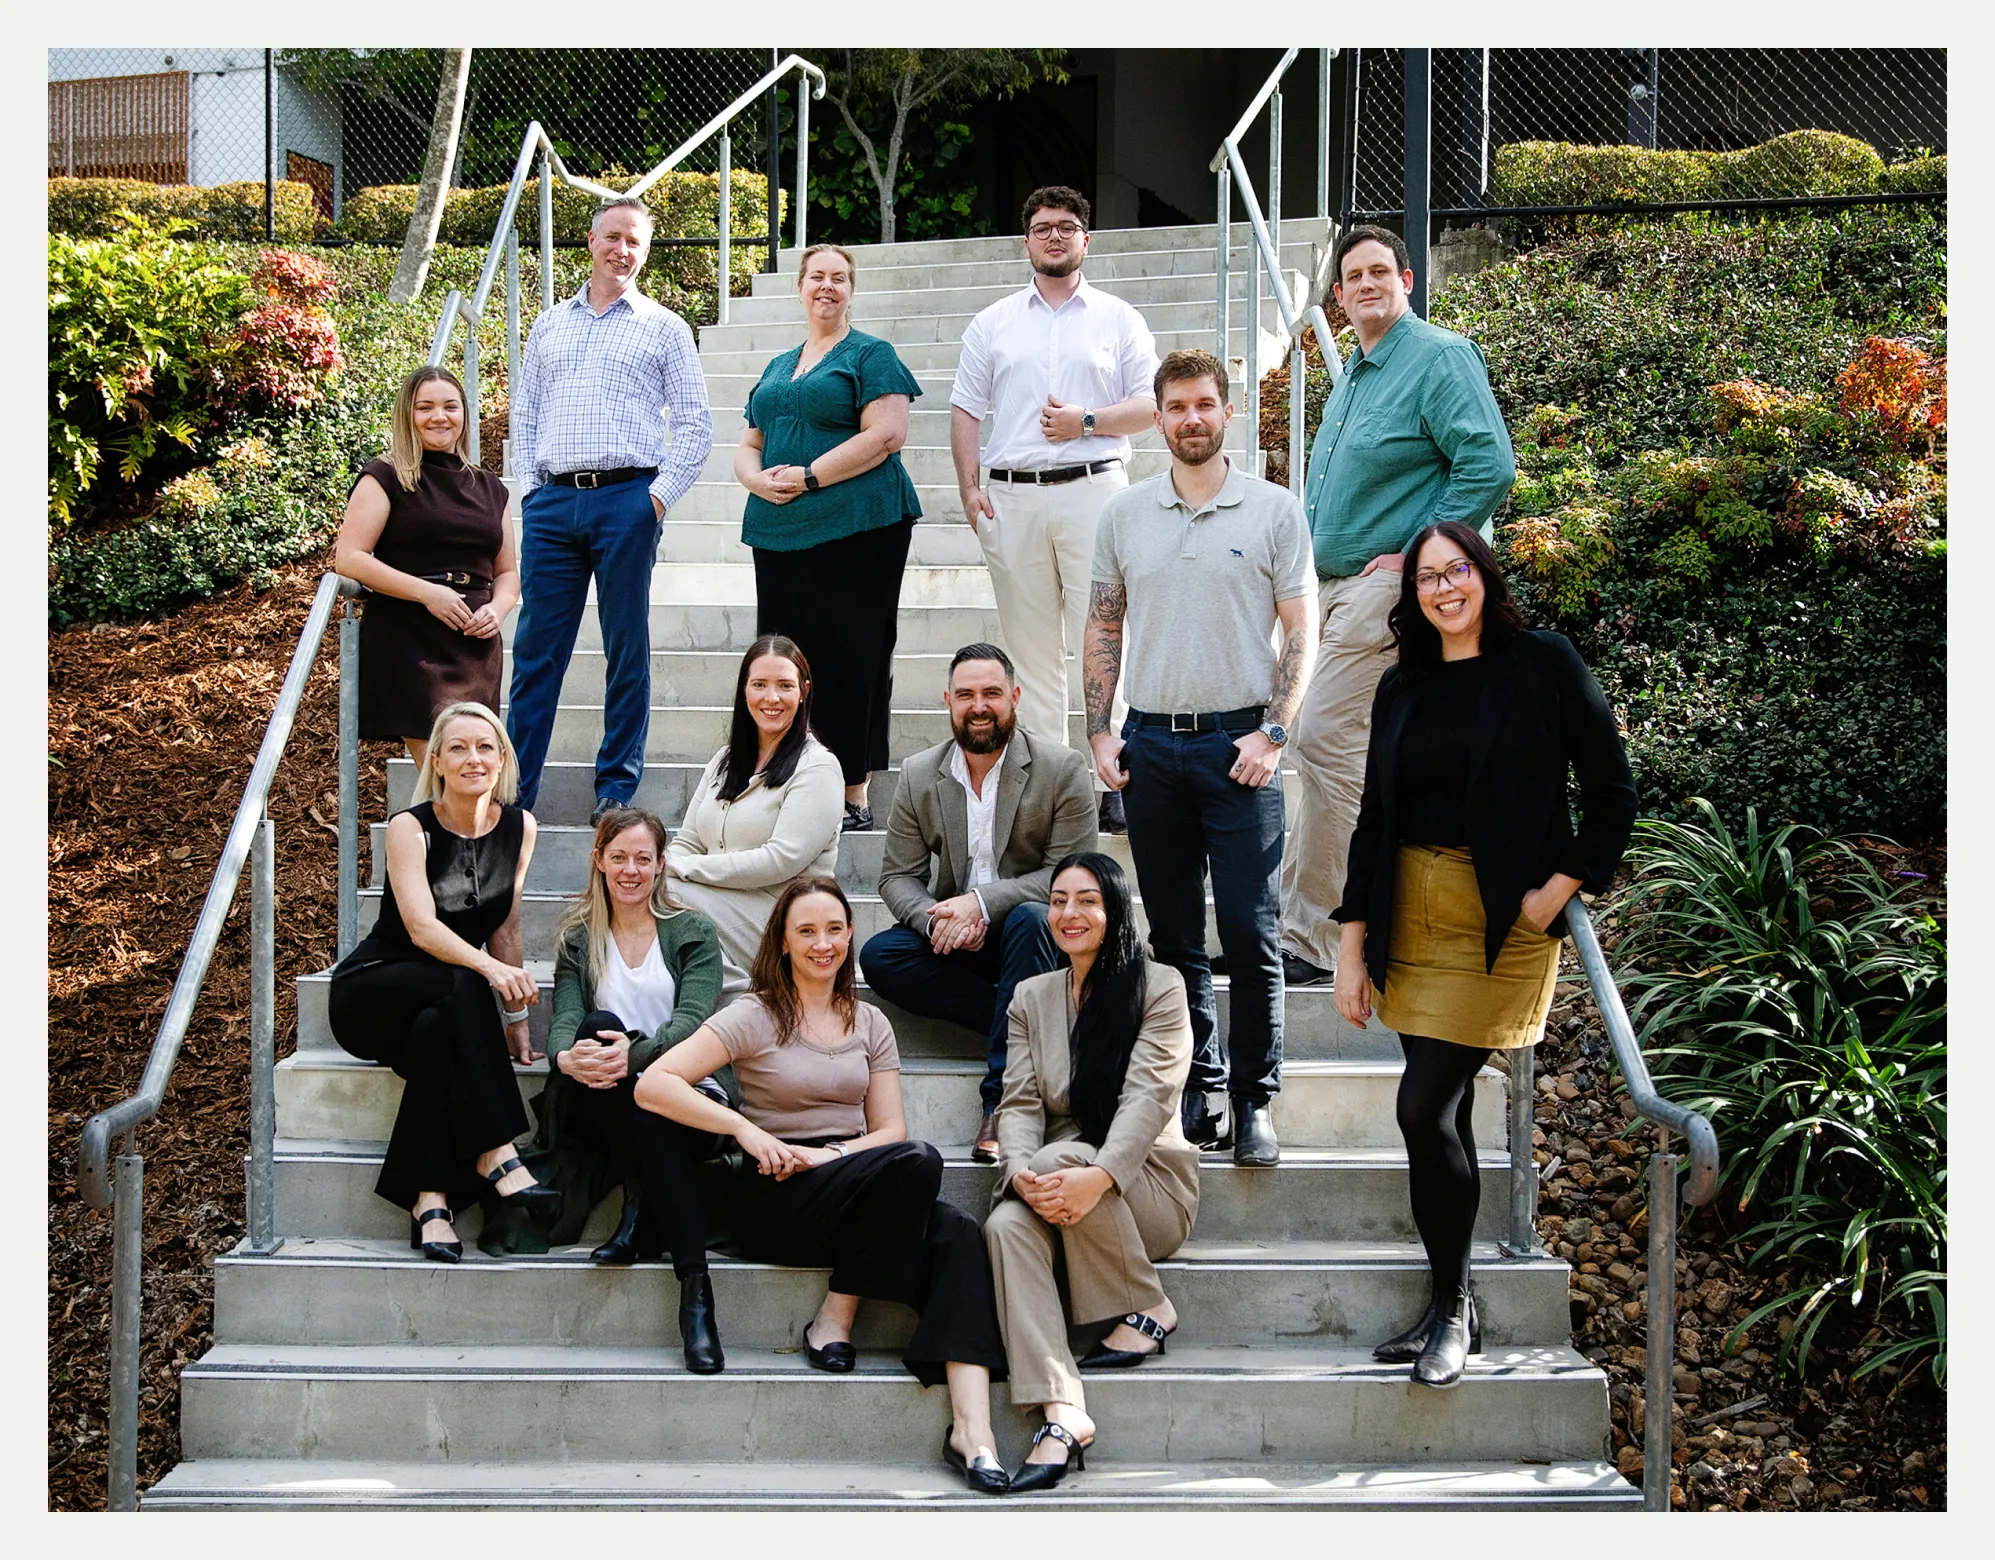
Meet Mel and the Zest team, who've helped hundreds of clients bridge the gap between selling and buying their next home.
A bridging loan lets you secure your next property while your current one is still on the market. Peak debt limits, how long you have to sell and whether interest is capitalised or paid monthly all vary between lenders, so the detail of the loan matters as much as the rate.
We explain how the numbers work for your situation and compare 60+ lenders to find a structure that gives you breathing room. Our team is based in Springfield and works with buyers across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe moving between homes should be just as simple as buying your first one. Here are a few recent Zest Google reviews we think you'll love!

A quick chat with Mel & the team works out how much bridging finance you would need and what it would cost you month to month. No cost, no obligation.

Peak debt limits, how long you have to sell, and whether interest is capitalised or paid monthly all vary between lenders. We compare across 60+ to find a structure that gives you breathing room.

Once you are ready, we coordinate the timing between your purchase and sale with the lender, so you are not left carrying two loans longer than you need to.


A bridging loan suits home owners who want to buy their next property before selling their existing one. It covers the gap between the purchase and the sale, so you're not forced to rent in between or rush the sale. It's often used by families upsizing or by people downsizing.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
We often see Springfield and Ipswich families upgrading to a larger block or a newer estate, and downsizers moving closer to Springfield Central or the Ipswich CBD. A bridging loan lets you secure the right home first without losing it while you wait for your sale.
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
The lender combines your current loan and the new purchase into one 'peak debt' while you sell. Once your current home sells, the proceeds pay down the loan to your end debt.
Many lenders let interest accrue (capitalise) on the bridging portion until your home sells, while you keep paying the end debt. Terms vary by lender.
Lenders set a maximum bridging period. If it runs out, they may ask you to reduce the price or refinance, so planning a realistic sale price matters.
Not always. Some buyers use equity in their current home as a deposit instead. We compare both approaches.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


