Whether you're buying your first investment property or expanding an existing portfolio, we'll help you find a loan structure that works with your strategy, not against it.
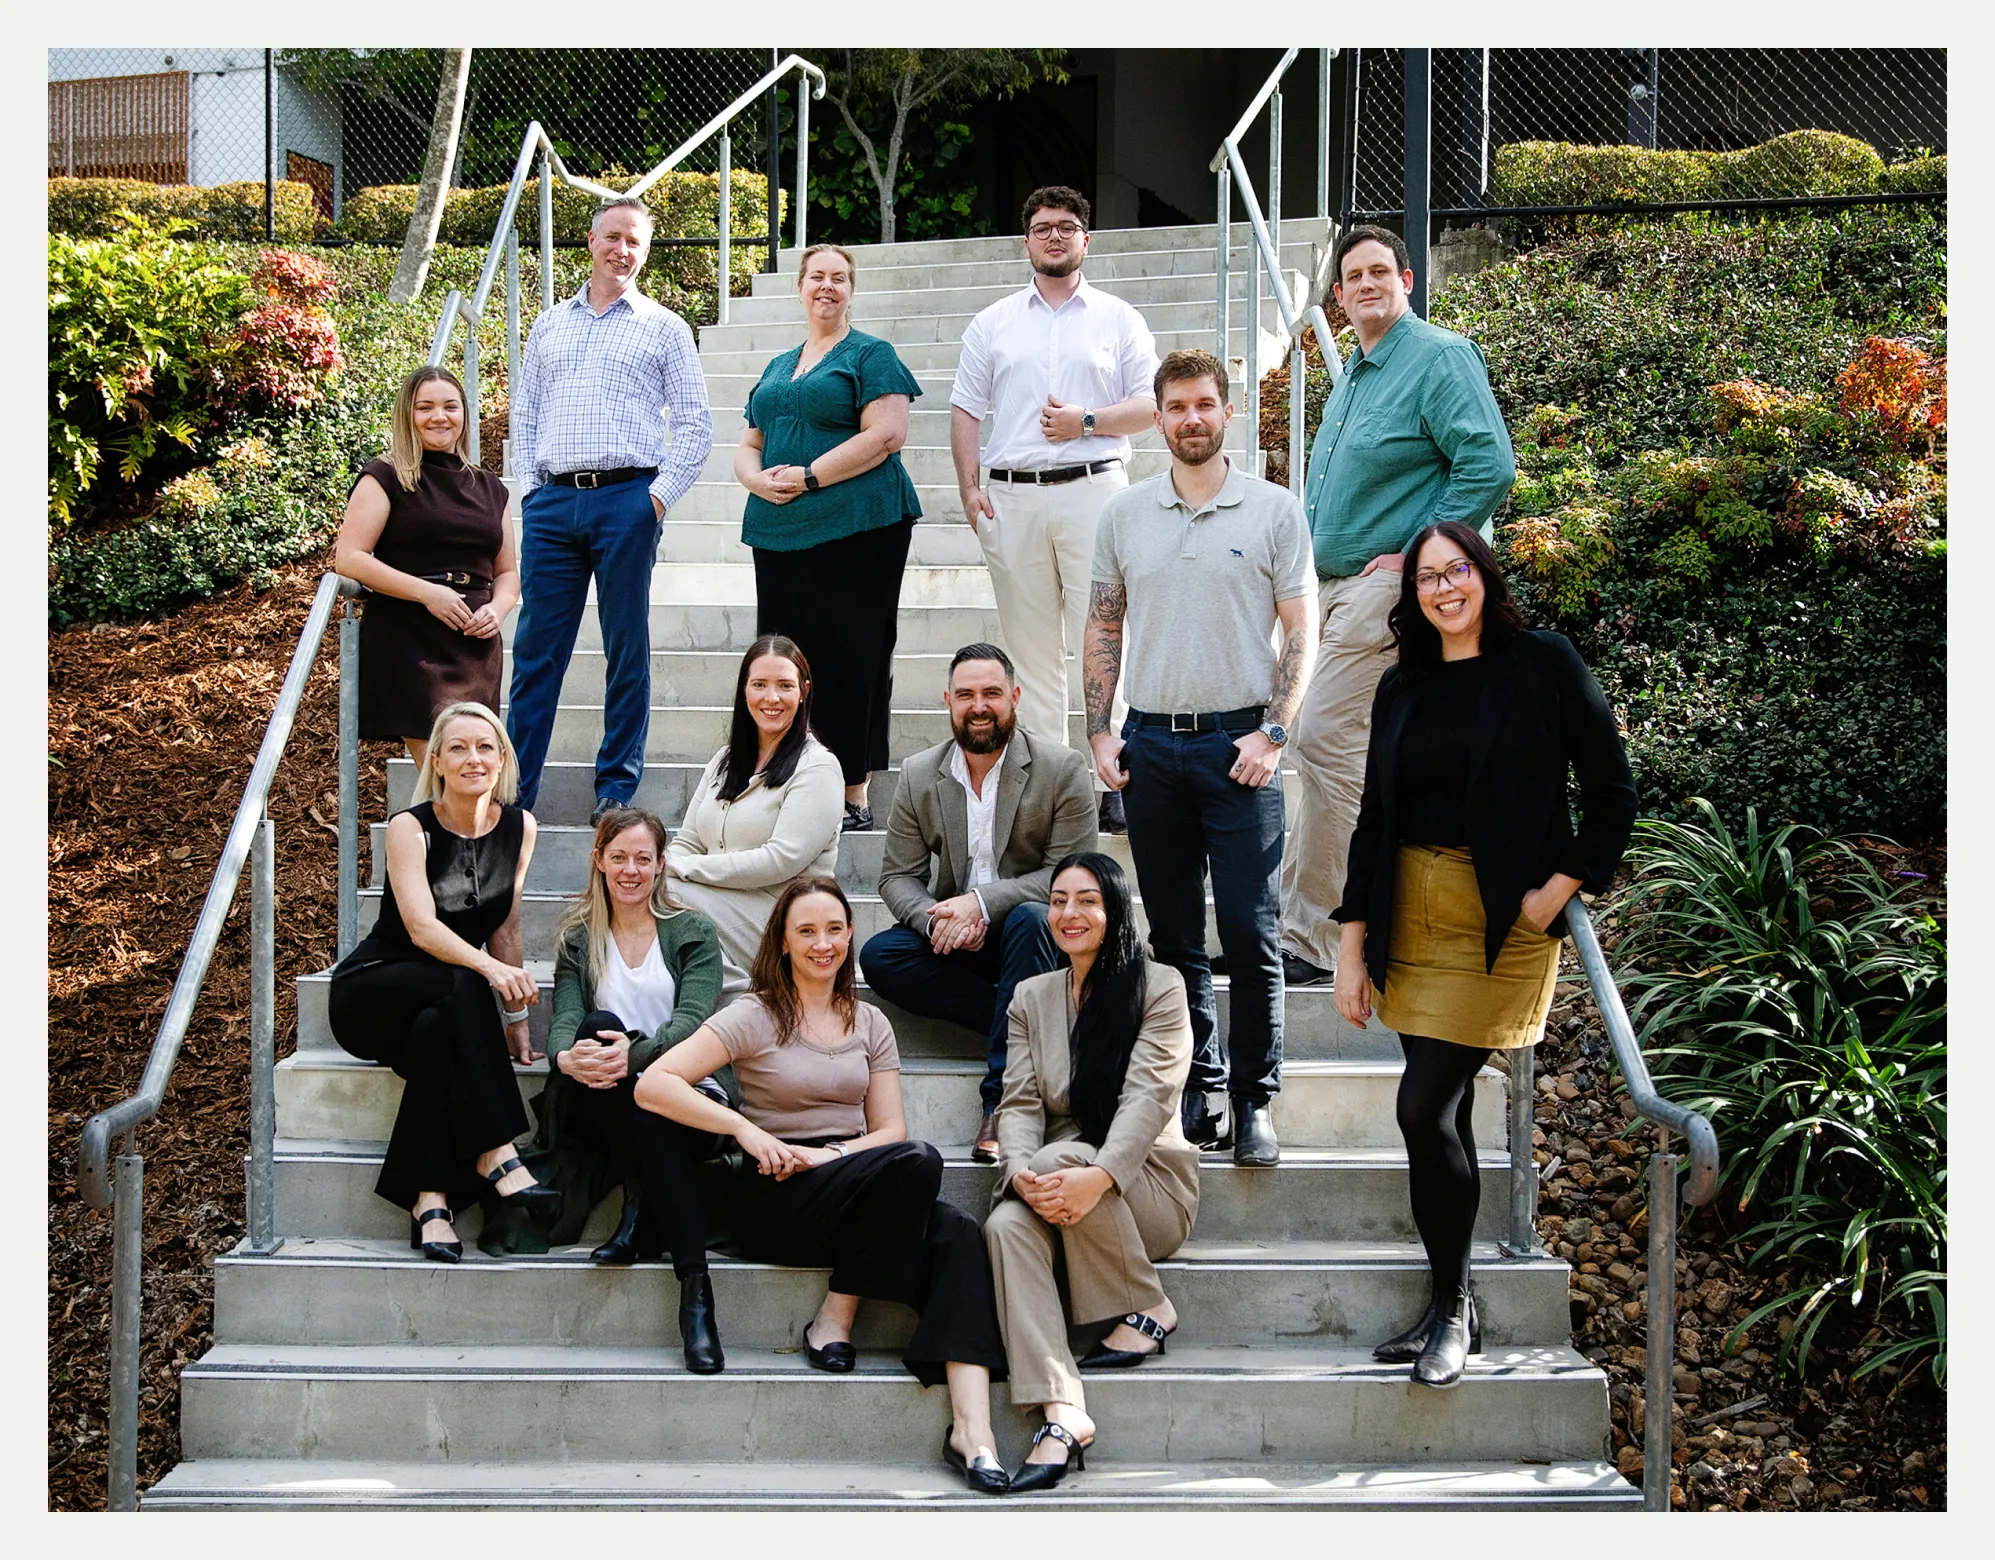
Meet Mel and the Zest team, who've helped hundreds of investors secure finance to grow their property portfolio.
Investment lending is not assessed the same way as a loan for your own home. Interest-only terms, how rental income is assessed and your borrowing capacity for a second or third property can vary significantly from bank to bank. The way your loans are set up now can also affect how easily you can buy again later.
Whether it is your first investment property or an addition to an existing portfolio, we compare 60+ lenders to find a loan structure that works with your strategy. Our team is based in Springfield and works with investors across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe growing your property portfolio should be just as simple as buying your first investment. Here are a few recent Zest Google reviews we think you'll love!

A quick chat with Mel & the team is the best place to start. We'll get to know your investment goals, look at your current position, and talk through what a lender is likely to approve. No cost, no obligation.

Not every lender treats investment loans the same way. Interest-only terms, rental income assessment, and borrowing capacity for a second or third property can vary significantly from bank to bank. We compare across 60+ lenders to find one that fits your strategy and doesn't hold back your next move.

Once we've matched you with the right lender, we handle the application, chase the paperwork, and keep you updated at every step through to settlement. If you're already juggling an existing loan, we can also look at how a new purchase affects your overall position before you commit.


Our investor loans suit anyone buying their first investment property or adding to a portfolio. Structure matters as much as rate, because how your loans are set up can affect tax, cash flow and your ability to buy again. Investing through super? See our SMSF property loan page.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
Investors are drawn to the Springfield and Ipswich region for its growth, transport links and new infrastructure. Areas like the Ripley Valley and Springfield Central have attracted strong interest, but every property needs to stack up on its own numbers.
Most of the investors we work with already own a home in Greater Springfield or the City of Ipswich and want to use the equity they have built to buy again. Before you look at properties, we work out how much usable equity you have, what a lender will count from the expected rent, and how a new loan would sit next to the loans you already hold. That tells you a realistic price range before you start inspecting.
Structure is where many investors get caught out. If a lender secures your new loan against your home as well as the investment, selling or refinancing one property later can mean revaluing both. Our guide to cross-collateralisation explains why we usually keep loans separate. We also talk through interest-only versus principal and interest terms, offset accounts and how many investment loans different lenders will allow, then suggest you check the tax side with your accountant.
The region offers very different types of investment property, from townhouses and units close to Springfield Central station to new house-and-land in the Ripley Valley and established homes in suburbs such as Redbank Plains and Goodna. Lenders treat these differently on valuation, deposit and the rent they will accept, so the right lender for a unit can be the wrong one for a house. If you are still deciding where to buy, read our guides to buying an investment property and rental yields by suburb.
You can meet Mel and the team at our Springfield office (Building 9, Level 1, 22 Magnolia Drive, Brookwater) or our Ipswich office (Level 3/16 East Street, Ipswich).
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
Yes. Many investors use equity in their home as the deposit, which can mean buying without saving a cash deposit.
It depends on your goals and cash flow. Interest only can improve cash flow in the short term, but you aren't reducing the debt. Speak with your accountant about the tax side.
Most lenders only count part of the expected rent when assessing your borrowing power, to allow for vacancies and costs.
Keeping loans separate and avoiding unnecessary cross-securing can give you more flexibility when you sell or buy again.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


