Not every lender assesses your history the same way. We know which ones are more likely to say yes.
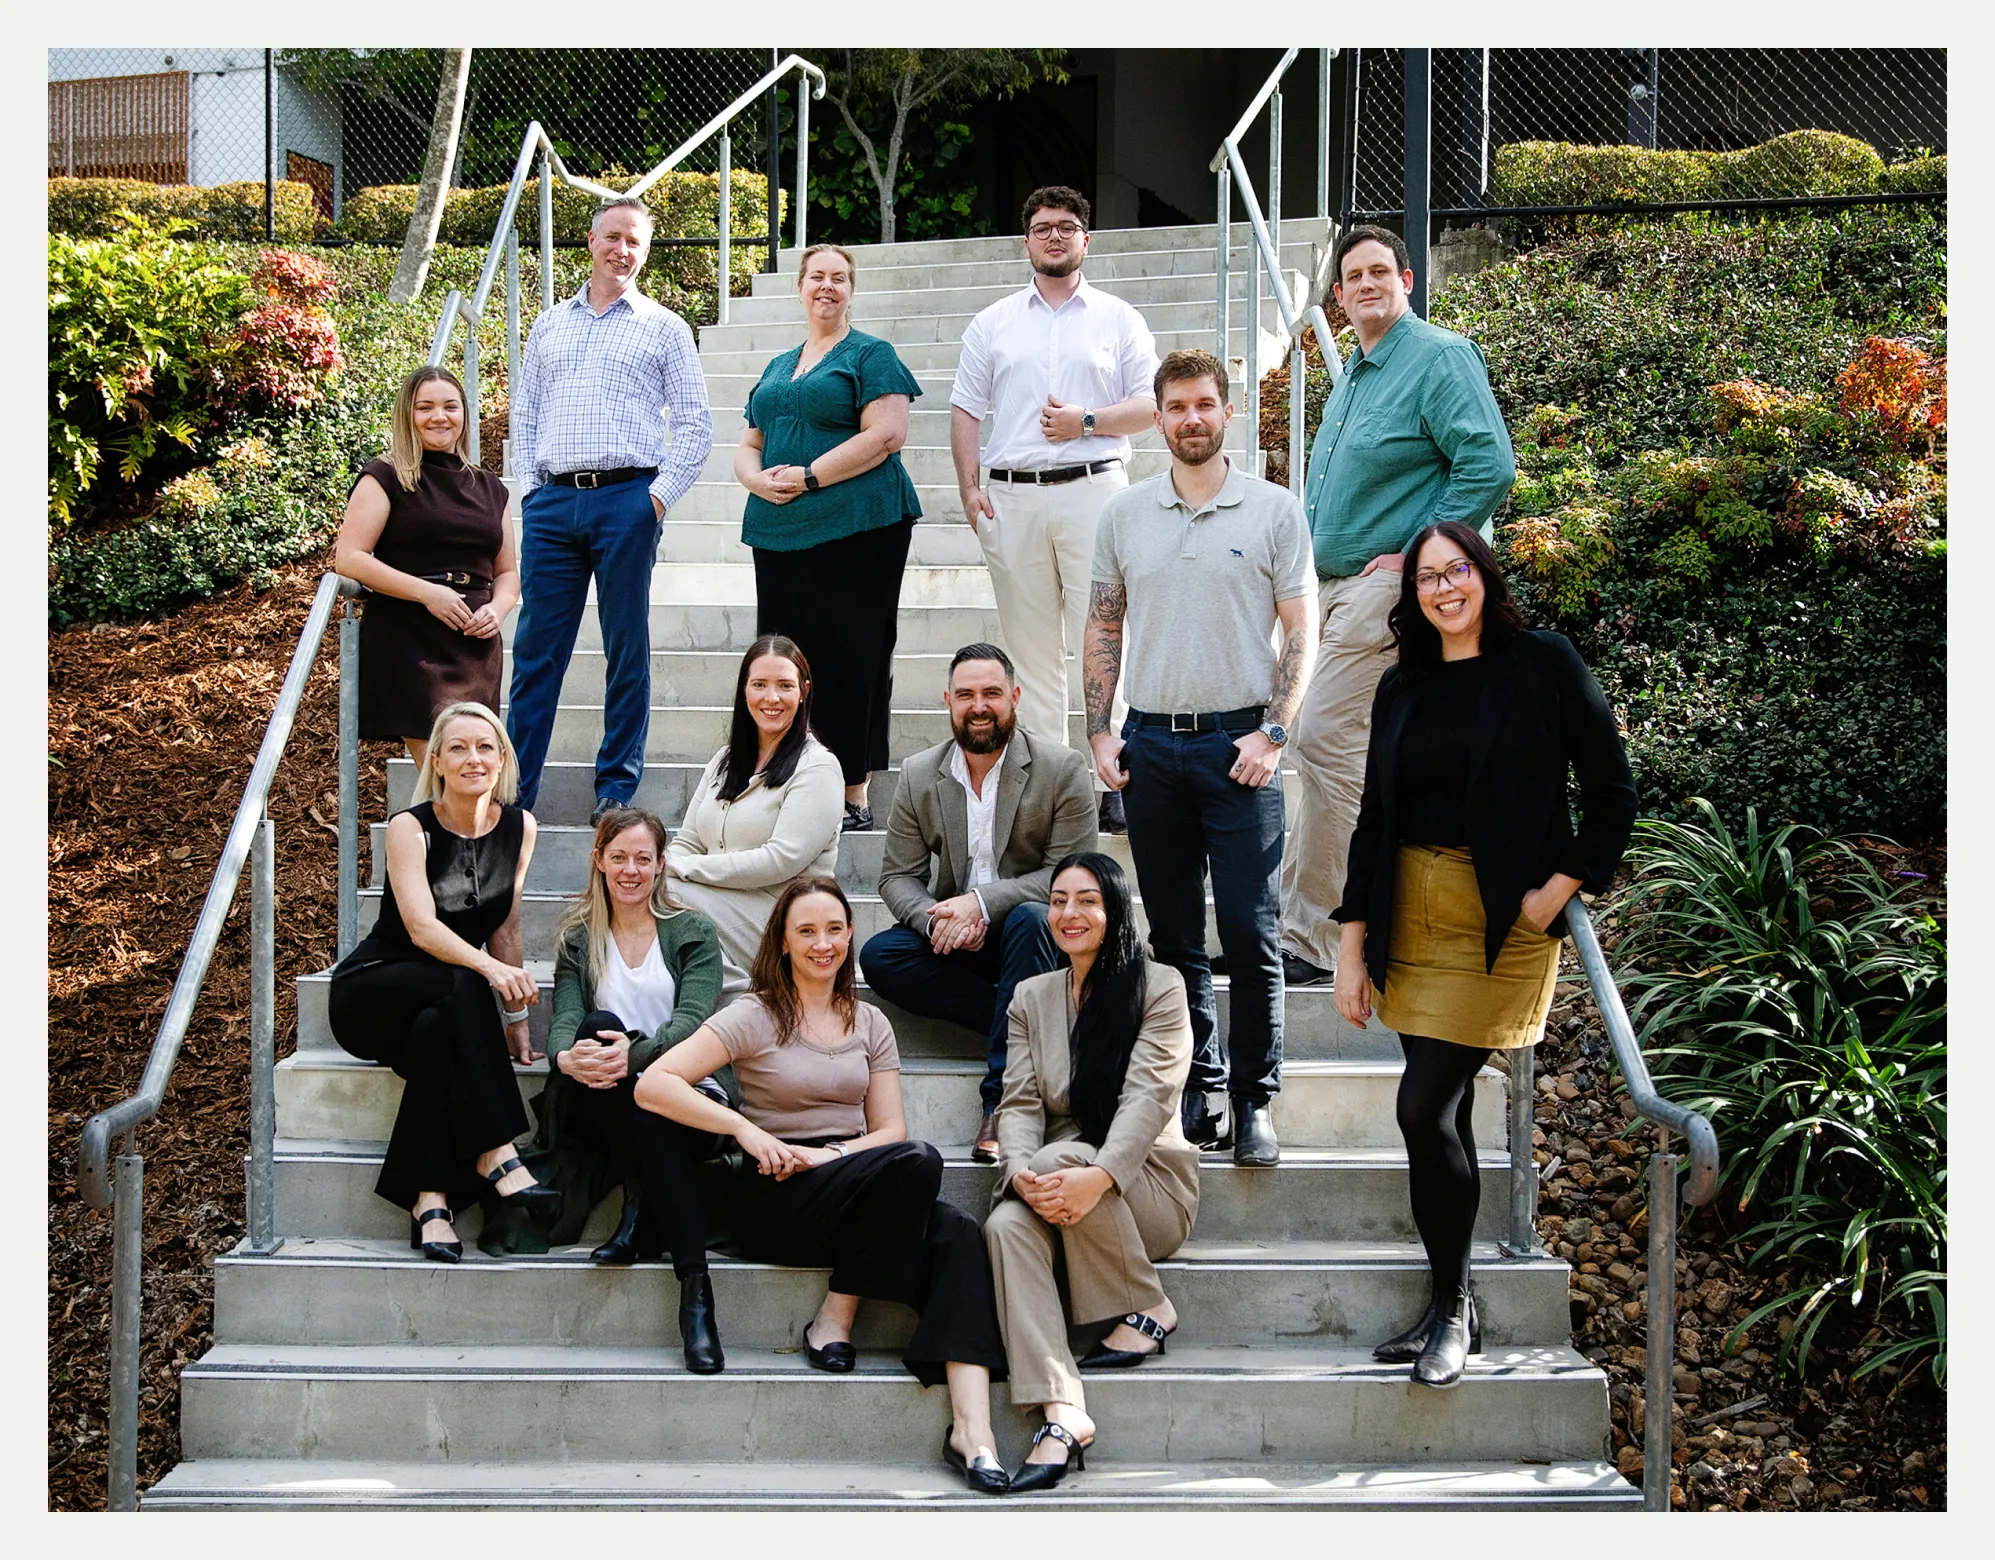
Meet Mel and the Zest team, who've helped hundreds of clients get finance approved despite a bumpy credit history.
Late payments, defaults or a bankruptcy discharge do not automatically rule you out, but they do change which lenders will consider your application. Lenders look at what happened, how long ago it was and how your finances have tracked since, and they do not all weigh those things the same way. Every application also leaves an enquiry on your credit file, so it pays to approach the right lender the first time.
We compare 60+ lenders, including those who specialise in second-chance lending, and talk through your options honestly before anything is lodged. Our team is based in Springfield and helps clients across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe a past credit issue shouldn't stop you from moving forward with confidence. Here are a few recent Zest Google reviews we think you'll love!

A confidential chat with Mel & the team costs nothing. We'll be upfront about where you stand and what your options actually look like.

Late payments, defaults or a bankruptcy discharge don't automatically rule you out. We compare across 60+ lenders, including those who specialise in second-chance lending, to find the right fit.

Once we've matched you with a lender that fits, we manage the application and give you a clear, honest picture of the process from start to finish.


Our past credit issue home loans suit people with defaults, late payments, judgments, or a past bankruptcy or debt agreement. Life happens, and a credit problem in the past doesn't always mean you can't get a home loan. If you're carrying several debts, see also debt consolidation.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
We help Springfield and Ipswich clients who've been knocked back by a bank and aren't sure where to turn. Specialist lenders can often help where major banks can't, and we can map out a plan to move to a mainstream loan later.
The first step is to look at your credit report together, not to apply. We want to know what is listed, when it was listed, whether it has been paid, and what has happened with your finances since. A paid default from several years ago with a clean record since is a very different story to a recent unpaid one, and lenders treat them very differently too.
Every application a lender receives can leave an enquiry on your credit file, and several enquiries close together can make the next lender more cautious. That is why we match you to a lender whose policy fits your situation before anything is lodged. Depending on your history, that may be a major bank, a smaller lender or a specialist lender that deals with defaults, discharged bankruptcy or a finished debt agreement. Specialist loans can cost more, so we also talk about a plan to move to a mainstream loan once your record allows.
We see this often across Springfield and Ipswich: a separation, a business that did not work out, a medical bill or a period of reduced income left a mark on someone's file, and they assumed a home loan was out of reach. Our guides explain home loans with defaults on your credit file, buying after bankruptcy and what to do after being declined.
We will be honest if now is not the right time, and tell you what to work on so you can apply with confidence later. You can speak with Mel and the team at our Springfield office in Brookwater or our Ipswich office on East Street.
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
Yes, some lenders will consider borrowers with defaults, especially if they're paid and you've had good conduct since. Rates may be higher.
It's possible once you've been discharged. Some specialist lenders consider recently discharged bankrupts.
Yes. Knowing what's on your report helps us choose the right lender and avoid unnecessary applications.
Not necessarily. Many borrowers refinance to a mainstream lender once their credit history improves.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


