Whether you're buying, refinancing or just reviewing your rate, we compare across 60+ lenders to find a home loan that matches how you actually earn and live.
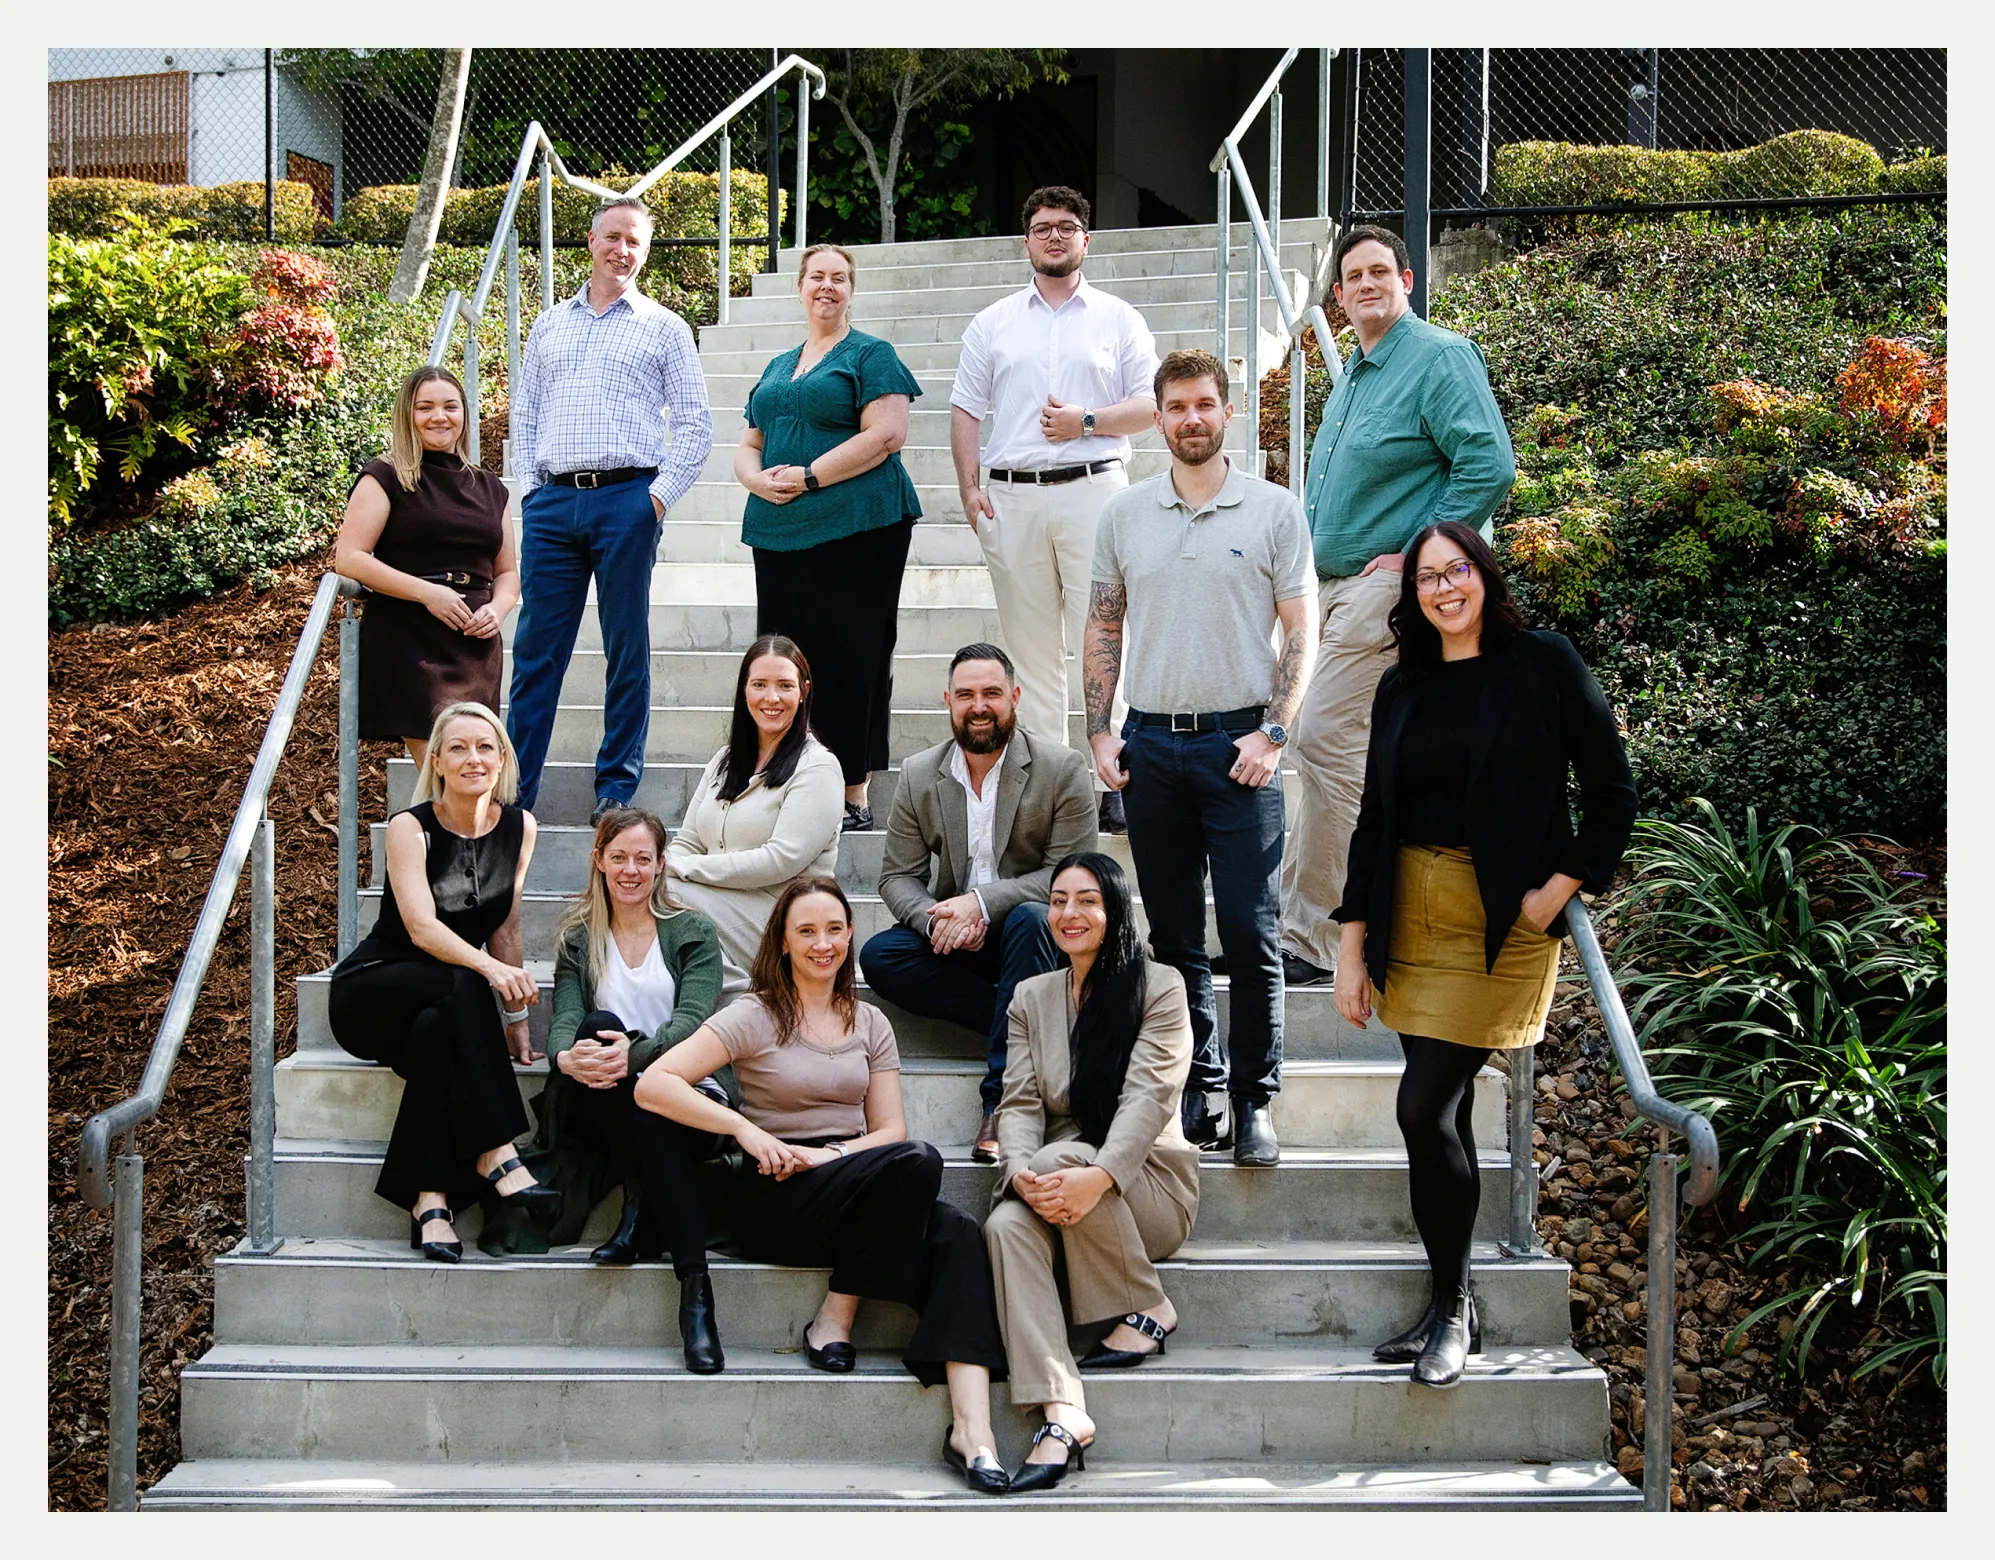
Meet Mel and the Zest team, who've helped hundreds of delighted clients get the home loans they want, and need.
A lot of applications stall because they go to one lender whose lending criteria was never a great match. Fixed or variable, offset or redraw, one loan or a split: the right structure comes down to your income and your goals, and it is worth working through before anything is lodged.
Whether you are buying, refinancing or reviewing your rate, we compare 60+ lenders to find a home loan that matches how you earn and live. You deal directly with Mel and the team, who are based in Springfield and work with clients across Springfield and Ipswich.

At Zest Mortgage Solutions, we believe buying a home, be it your first or fifth, should be simple and stress-free. Here are a few recent Zest Google reviews we think you'll love!

A quick call with Mel & the team gets you a real borrowing figure, not a rough online guess, along with what repayments would actually look like at today's rates. No cost, and no obligation to apply.

A lot of applications stall because they go to one lender whose lending criteria was never a great match. Fixed or variable, offset or redraw, one loan or a split: the right structure comes down to your income and goals, and we work through it with you before anything is lodged.

Once you decide to go ahead, we prepare the application, manage the back and forth with the lender and keep you updated right through to settlement, so you are not chasing paperwork or repeating yourself to anyone.


A standard home loan suits most people buying a home to live in, whether it's your first, second or fifth purchase. The right loan depends on your deposit, income, repayment preferences and how long you plan to stay, so we start there rather than with a rate.
Every lender is different, so we'll confirm the exact list for your situation before you apply.
Springfield and Ipswich have a mix of established homes, newer estates and house and land packages, and lenders don't always view them the same way. A loan that suits an established home in Ipswich may differ from one for a new build in Ripley or Springfield Rise. If you're buying for the first time, see our first home loan page, or if you're ready to make offers, start with a home loan pre-approval.
Springfield and Ipswich are not one property market. Greater Springfield, including Springfield Lakes, Springfield Central, Augustine Heights and Brookwater, is a master-planned community with mostly newer homes, townhouses and some units. The wider City of Ipswich adds older homes close to the Ipswich CBD, fast-growing estates in the Ripley Valley and acreage on the city's edges. Lenders can treat each of these differently on valuation, deposit and the type of security they will accept, which is why we look at the property as closely as we look at you.
Before you start making offers, we work out a realistic borrowing figure from your actual income, debts and living costs, then show you how that changes with different deposits and loan structures. We compare 60+ lenders and explain the trade-offs between a variable rate, a fixed rate or a split loan, and whether an offset account or redraw suits the way you manage money. Then we help you get a pre-approval so you know your limit before auction day or before you sign a contract.
Buying a house and land package or a new build? Construction loans are paid out in stages as the build progresses, so the lender and the builder's payment schedule need to line up. Our construction loans page explains how that works. If you already own a home and want a better fit, see refinancing.
We have two local offices: our Springfield office at Building 9, Level 1, 22 Magnolia Drive, Brookwater, and our mortgage broker Ipswich office at Level 3/16 East Street in the Ipswich CBD. You can also call us on (07) 3461 6499.
Want to talk it through? Book a free chat with Mel and the Zest team, or call (07) 3461 6499.
Many lenders accept a deposit of 5% to 10%, but borrowing more than 80% of the property value usually means paying lenders mortgage insurance (LMI). A 20% deposit avoids LMI with most lenders. Some government schemes let eligible buyers buy with a smaller deposit without LMI.
A variable rate moves with the market and usually allows extra repayments and an offset account. A fixed rate gives certainty for a set period but often limits extra repayments. Many borrowers split their loan to get some of both.
No. Zest is paid by the lender you choose once your loan settles, so our service is free for home loan clients.
It varies by lender and how complete your paperwork is. Having your documents ready at the start is the easiest way to speed things up.
Yes. Most house and land purchases use a construction loan for the build, which pays the builder in stages, alongside the land purchase. Lenders look at the building contract and the builder as well as your income and deposit.
Our offices are in Brookwater and the Ipswich CBD and most of our clients live or buy in Springfield and Ipswich, but we can also arrange home loans for properties elsewhere in Queensland.
Please just complete your details below

"Thank-you! As first home owners we were very unsure of the process. However, from our very first encounter with Mel, we felt comfortable and certain that we had chosen the right broker for us. Ashleigh helped us through the application process and was always prompt with emails/ phone calls and more than willing to answer our questions. You guys truly are amazing 🤩"

"Thanks to the fantastic team at Zest Mortgage Solutions. They made an incredibly complex business investment purchase extremely easy for us and kept us up to date with the process as it moved forward. I would highly recommend them and will be utilising their services in the future."

"Mel and the team have been amazing throughout the entire process. We were constantly informed and nothing was too difficult. It really couldn't have been a better experience. We would highly recommend Zest Mortgage Solutions!"

"Mel and the team at Zest Mortgage Solutions make the process of buying a house easy, there was always someone there to assist or answer questions - even during the festive season 😊 thanks team, 💯 recommend"

"As a single mother, I never thought in a million years I could own my own home. Melissa and her team made the process so easy and stress free. I can’t thank them enough for making my dreams come true. No question was to dumb and they never made me feel like I was bothering them with all my calls for clarification! Would 10/10 recommend them to anyone looking to purchase a house."


